 分享:


The co-authored paper by Associate Professor Jianfeng An, a researcher at the base, Professor Minggui Yu, Co-Director, and Mengmeng Zhang of Huazhong University of Science and Technology, titled “Banking Capital Regulation Reform and Local Government Bond Financing Costs—Improving the Long-Term Mechanism for Government Debt Management,” was published in Journal of Financial Research, Issue 9, 2026 (Total Issue No. 555), an A-Class journal recognized by our university.
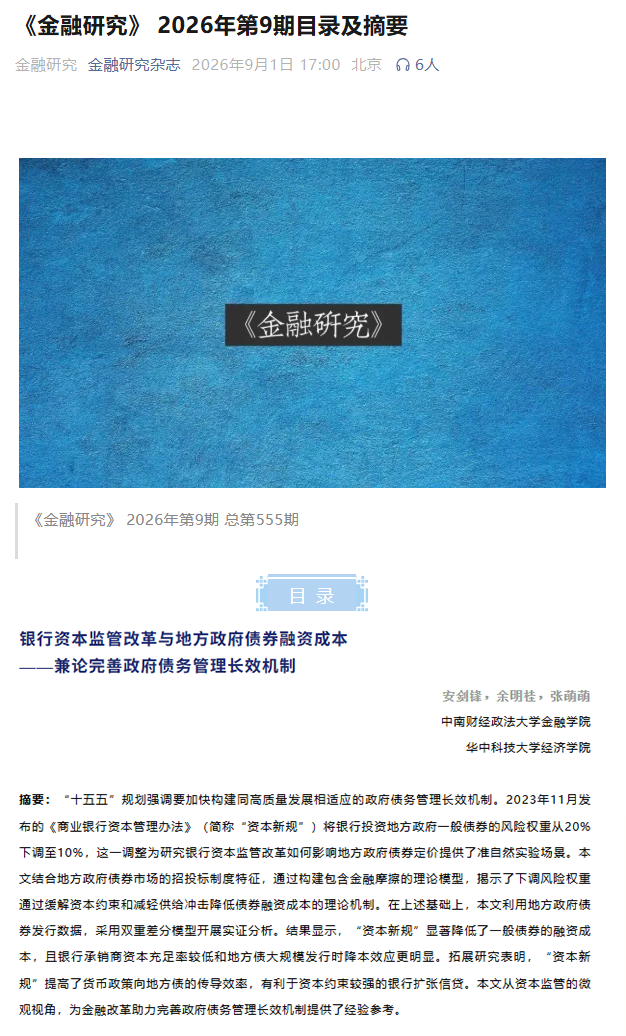
Journal of Financial Research is an authoritative journal in China’s finance field. Founded in 1958, it is supervised by the People’s Bank of China and sponsored by the China Society for Finance and Banking. The journal focuses on the frontiers of financial reform and development, publishing high-level research that emphasizes both theoretical and policy relevance. It is indexed by CSSCI and the Peking University Core Journals, and has won the National Journal Award, exerting significant influence in academia and policymaking circles.
Content Summary
The Outline of the 15th Five-Year Plan for National Economic and Social Development of the People's Republic of China explicitly states that China should accelerate the establishment of a long-term mechanism for government debt management compatible with high-quality development. This indicates that the local government debt issue is not merely a matter of short-term risk disposal, but an institutional issue concerning fiscal sustainability, financial stability, and high-quality development. In recent years, China has emphasized countercyclical adjustment through proactive fiscal policy, yet local governments have faced tight fiscal positions. Against this backdrop, how to reduce the financing costs of local government bonds by deepening coordinated fiscal and financial reforms has become an important practical issue that urgently needs to be studied. As a core vehicle connecting fiscal funding demand and financial capital supply, the development of the local government bond market is subject to the dual influence of fiscal institutional arrangements and financial market reforms. However, existing studies mostly focus on fiscal institutions, information disclosure, or administrative incentives, analyzing how local fiscal characteristics and government behavior affect debt costs, while few studies have examined financial market reform, especially how bank capital regulation affects the financing conditions of local government bonds.
In fact, banks are the most important investors in China’s local government bond market, holding more than 70% of local government bonds. Local government bonds are divided into general bonds and special bonds. Before the official release in November 2023 of the new version of the Administrative Measures for the Capital of Commercial Banks (hereinafter referred to as the “New Capital Rules”), the risk weights for bank investments in both general bonds and special bonds were 20%, reflecting no risk differentiation between the two. To achieve differentiated regulation, the New Capital Rules lowered the risk weight of general bonds from 20% to 10%, while keeping the risk weight of special bonds unchanged at 20%. This adjustment helps align risk characteristics with capital regulation. Logically, the New Capital Rules may incentivize banks to invest more heavily in general bonds in primary market bidding, thereby reducing the issuance costs of general bonds; however, its actual impact still requires rigorous and systematic research.
Against the above background, this paper focuses on the following core questions: whether the reduction in the risk weight of local government general bonds under bank capital regulation lowers the financing costs of local government general bonds, and through what mechanisms this effect operates. To address this question, this paper first constructs a partial equilibrium model characterizing the bidding decisions of a representative bank, and analyzes the impact of risk weight adjustments on local government bond pricing. This paper derives the core conclusion that a lower risk weight reduces the financing costs of general bonds, and further reveals the theoretical mechanism through which the decline in financing costs is achieved—by alleviating bank capital constraints and mitigating local government bond supply shocks. Building on the theoretical analysis, this paper further employs a difference-in-differences approach to conduct empirical research, systematically examining the impact of the implementation of the “New Capital Rules” on the issuance costs of general bonds, as well as its mechanisms and economic consequences.
This paper finds the following: First, the implementation of the “New Capital Rules” significantly reduced the issuance spread of general bonds, implying that the reduction in risk weights significantly lowered the financing costs of general bonds. This conclusion remains valid after a series of robustness checks. Second, event study analysis shows that after the release of the New Capital Rules, the excess credit spread of general bonds was significantly negative, and the reduction was larger when the bond issuance maturity was longer, the issuance scale was larger, and regional fiscal pressure was greater. Third, mechanism analysis shows that, consistent with the theoretical model, the New Capital Rules significantly reduced the financing costs of general bonds by alleviating bank capital constraints and mitigating the shock of local government bond issuance on the market’s absorption capacity (i.e., the “supply shock”). Fourth, research on other effects of the New Capital Rules finds that after their release, the sensitivity of the winning bid rate of general bonds to the market benchmark interest rate increased, and the credit scale of banks with lower capital adequacy ratios expanded.
Author Introduction
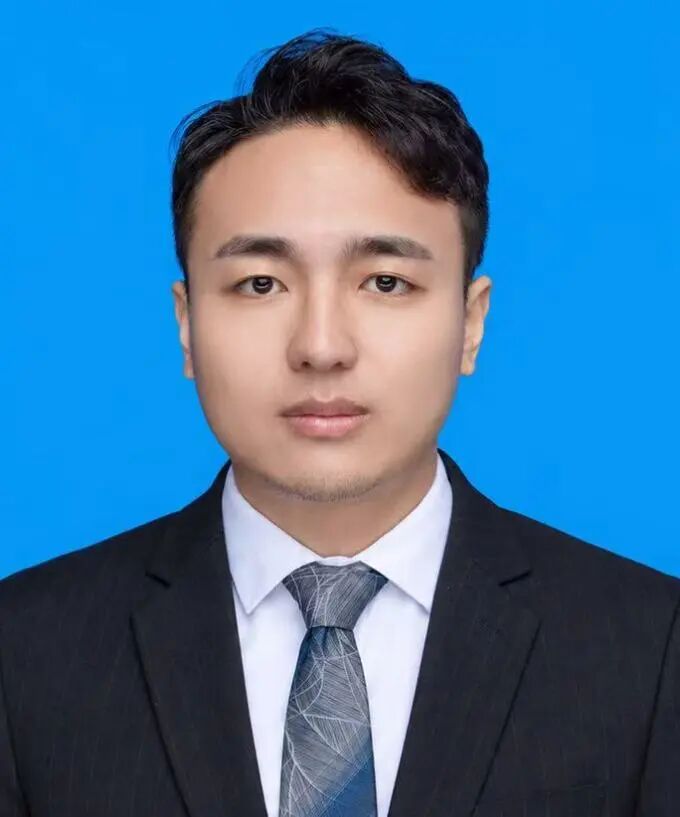
Jianfeng An is an Associate Professor at the School of Finance, Zhongnan University of Economics and Law, and a Wenlan Young Scholar. His research has been published in journals such as Management World, Economic Research Journal, Journal of Financial Research, China Industrial Economics, and Finance & Trade Economics. A research report he co-authored received an affirmative instruction from central leadership and was adopted by internal publications of the National Development and Reform Commission. Several of his papers have won honors including the 2024 China Finance Excellent Paper Award, the First Prize of the China Investment Annual Conference, and the Outstanding Paper Award of the Beijing Financial Street Forum.
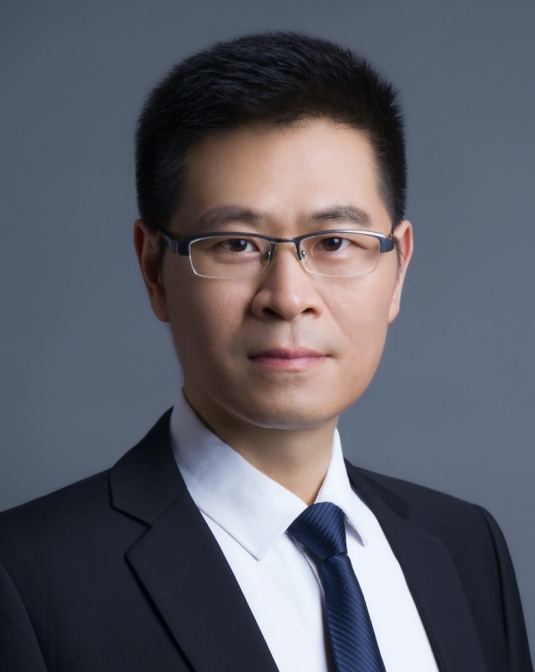
Professor Minggui Yu is Dean and Doctoral Supervisor of the School of Finance, Zhongnan University of Economics and Law, Chief Expert of a Major Project of the National Social Science Fund of China, and a recipient of the Ministry of Education’s New Century Excellent Talents in University program. His research fields include digital finance, finance and artificial intelligence, corporate finance, and finance and innovation. He has published more than 90 academic papers in many authoritative domestic and international journals, including Economic Research Journal, Management World, The Journal of World Economy, China Economic Quarterly, Journal of Financial Research, China Industrial Economics, Accounting and Finance, Pacific-Basin Finance Journal, and Economic Modelling. He has led more than 10 projects, including Major Projects of the National Social Science Fund of China, Key Projects of the National Social Science Fund of China, and projects funded by the National Natural Science Foundation of China.
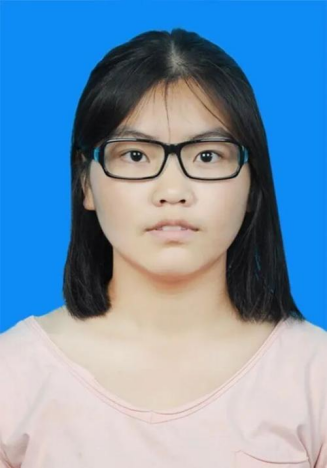
Mengmeng Zhang is a Lecturer at the School of Economics, Huazhong University of Science and Technology. Her research has been published in journals such as Economic Research Journal, Journal of Financial Research, China Industrial Economics, Finance & Trade Economics, and Studies of International Finance.