 分享:


(Corresponding student: Yiting Wang) On July 3, 2026, the 59th session of the "Digital Technology and Economic Finance Frontier Forum" was successfully held in Conference Room 401, South Wing, Wenquan Building. The session featured Associate Professor Lei Zhao from ESCP Business School as the invited speaker, who delivered a presentation titled "Market-Level Tug of War and Asset Pricing." Professor Xianming Sun, Associate Dean of the School of Finance and Executive Deputy Director of the Innovation and Talent Base for Digital Technology and Finance, chaired the session, with over 30 faculty members and students attending in person.
The session officially commenced after a brief opening remark by Professor Xianming Sun. Associate Professor Lei Zhao then focused on the core relationship between trading behavior in capital markets and asset pricing, emphasizing that asset pricing is a central research area in modern financial economics, crucial for understanding the operating mechanisms of capital markets, analyzing market price fluctuations, and refining theoretical frameworks in finance. Traditional asset pricing studies have largely concentrated on single influencing factors, leaving room for further exploration of intraday versus overnight traders' strategic interactions and the differential effects of market noise on pricing mechanisms.
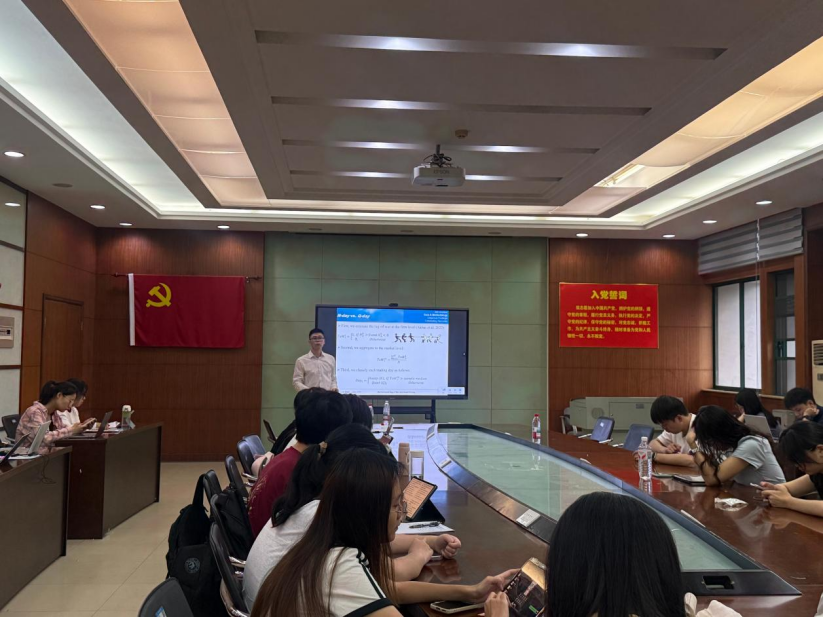
Subsequently, Associate Professor Lei Zhao systematically elaborated on the core ideas, innovative methodologies, and empirical findings of this study. Leveraging the market-level tug‑of‑war between overnight traders and intraday traders, Associate Professor Zhao and his team constructed a parsimonious and efficient indicator function, innovatively categorizing trading days into two scenarios: tranquil trading days and noisy trading days. Through extensive empirical data analysis and robustness tests, the team arrived at a groundbreaking conclusion: on tranquil trading days, the Security Market Line (SML) exhibits an upward‑sloping pattern, consistent with the core logic of traditional asset pricing theory; on noisy trading days, however, the SML takes on a distinct downward‑sloping shape, challenging the conventional unidimensional understanding of the theory.
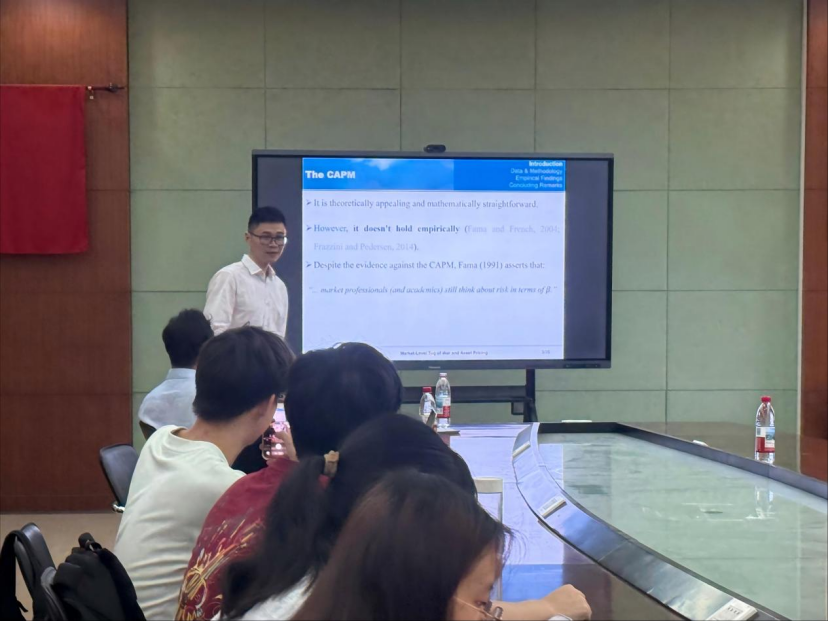
Furthermore, Associate Professor Lei Zhao supplemented the presentation with multiple extended tests to verify the generalizability and scientific robustness of the findings. The study confirmed that this differentiated pricing pattern holds not only on important information dates—such as the implementation of macroeconomic policies and corporate earnings announcements—but also on regular trading days. This result casts new doubts on and offers complementary insights to several prevailing explanations in the existing literature, effectively enriching the theoretical framework of asset pricing. In addition, the team constructed a mechanism model grounded in the overcorrection hypothesis to fully elucidate the intrinsic logic behind the pricing differentiation across the two types of trading days, thereby providing solid theoretical support and a coherent mechanistic interpretation for their conclusions.
During the Q&A session, faculty and students in attendance engaged in in-depth discussions on topics such as model assumptions, asset pricing discrepancies, and market game mechanisms. Attendees universally expressed that the lecture had deepened their understanding of asset pricing and provided valuable reference points for the development of financial markets.
Finally, Professor Yongbin Lyu expressed his gratitude to Professor Wenli Xu for his insightful sharing. This lecture clearly deconstructed the underlying logic of how AI agents are reshaping economic research—not only demonstrating the efficiency gains brought by digital tools, but also clarifying the bottom line and core values of academic inquiry. The faculty and students present all agreed that the lecture was both cutting‑edge and practical, helping to define the boundaries of AI tool usage and offering clear, feasible guidance for future empirical paper writing and academic research.
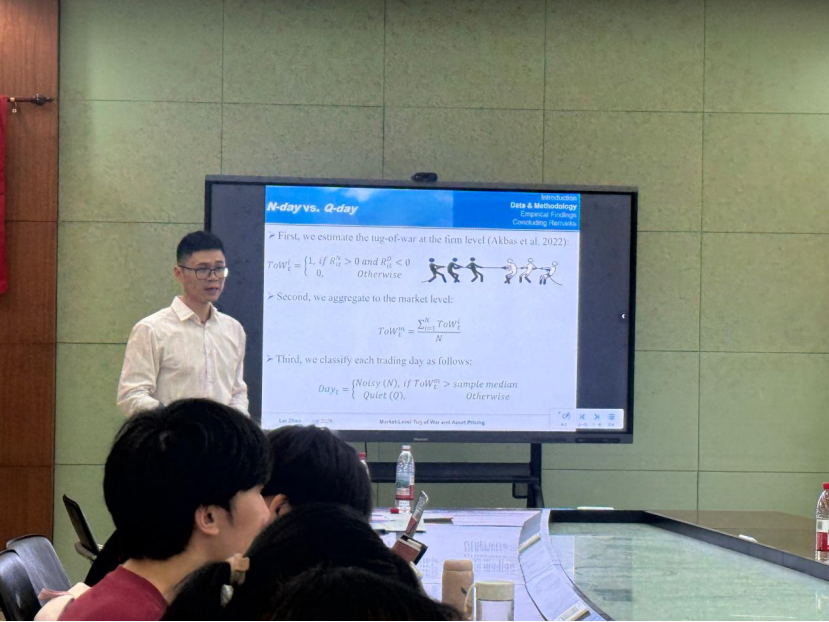
Finally, Professor Xianming Sun expressed his gratitude to Associate Professor Lei Zhao for the insightful presentation and emphasized that asset pricing remains a key direction in financial research, with future efforts continuing to promote both scholarly inquiry and collaborative work in this area. The lecture concluded successfully on this note.
Speaker Introduction
Lei Zhao is an Associate Professor at ESCP Business School. His primary research interests include banking, asset pricing, and corporate finance. He has published in international journals such as the Journal of Financial and Quantitative Analysis, the Journal of Economic Behavior and Organization, and the Journal of International Money and Finance. His work on government implicit guarantees was shortlisted for the Leke van den Burg Prize awarded by the Scientific Advisory Council of the European Securities Commission in 2015, and his paper on crude oil storage costs received the Best Paper Award at the 2023 Annual Conference of the Commodity and Energy Markets Association.
Frontier Forum for Digital Technology and Finance introduction
Recent years have witnessed a dramatic acceleration in a digital revolution in economic sectors and a rapid adoption of the new generation of information technologies, such as artificial intelligence, blockchain, cloud computing, big data, etc. These technologies effectively set off the digital economy. It has become a key driving force in creating global economic growth, improving the modernization level of governance capabilities, and promoting high-quality economic development in China. In particular, digital finance is the most important part of the digital economy. To explore the development direction of the cross-integration of digital technology and finance, the Innovation and Talent Base for Digital Technology and Finance is hosting the “Frontier Forum for Digital Technology and Finance”, in collaboration with the School of Finance, Wenlan School of Business, Economics School, School of Information and Safety Engineering, School of Statistics and Mathematics, School of Public Finance and Taxation of Zhongnan University of Economics and Law (ZUEL). This lecture series will invite the well-known scholars at home and abroad in digital technology, digital economy, digital finance, and other related fields as guest speakers, providing an open and cutting-edge academic exchange platform for interdisciplinary research on digital technology and finance.