 分享:


The 59th Frontier Forum on Digital Technology and Economic Finance
Topic: | Market-Level Tug of War and Asset Pricing |
Speaker: | Lei Zhao, Associate Professor ESCP Business School |
Host: | Xianming Sun, Professor School of Finance, Zhongnan University of Economics and Law Innovation And Talent Base For Digital Technology And Finance |
Time: | 10:30-12:00, Friday, July 3, 2026 |
Location: | 401 Conference Room Wenquan South Building |
Abstract: We propose a simple indicator function based on the aggregate tug-of-war between overnight and intraday traders, and use it to identify two types of trading days: quiet and noisy days. We analyze these days and document that the security market line is upward sloping on quiet days and downward sloping on noisy days. This result is robust to a number of additional tests. Moreover, the result holds on both (i) important macroeconomic and earnings news days and (ii) other days, challenging some proposed explanations in the literature. We present and test a mechanism based on the over-correction hypothesis to rationalize the finding.
Speaker Introduction:
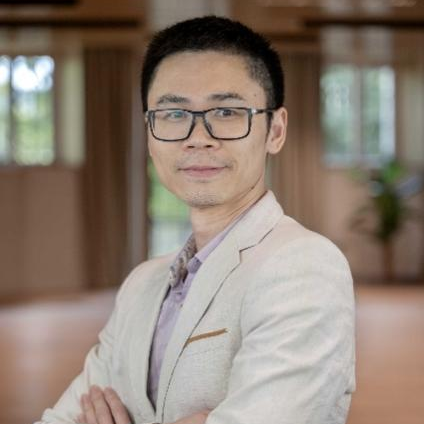
Lei Zhao is an Associate Professor at ESCP Business School. His main research areas include banking, asset pricing, and corporate finance. His research has been published in international journals such as the Journal of Financial and Quantitative Analysis, Journal of Economic Behavior and Organization, and Journal of International Money and Finance. His research on government implicit guarantees was shortlisted for the Ieke van den Burg Prize awarded by the Scientific Committee of the European Securities and Markets Authority (ESMA) in 2015, and his research paper on crude oil storage costs won the Best Paper Award at the 2023 Annual Meeting of the Commodity and Energy Markets Association.